

Table of Contents
- Understand Common IRS Audit Triggers and Red Flags
- Step 1: Reconcile All Income Sources and Information Returns
- Step 2: Document Rental Property Tax Deductions Thoroughly
- Step 3: Establish Real Estate Investor Tax Recordkeeping Systems
- Step 4: Know How Long to Keep Rental Property Tax Records
- Step 5: Report Investment Losses Accurately and Support Them
- Step 6: Avoid Unusually Large or Inconsistent Deductions
- Step 7: Respond Promptly to Audit Notices
- Frequently Asked Questions
Last Updated: October 8, 2026
Understand Common IRS Audit Triggers and Red Flags
IRS audits happen more often than many investors realize. The agency uses data analytics and specific patterns to flag high-risk filings, so understanding the triggers is your first line of defense.
Large deductions relative to income, inconsistent year-over-year reporting, and unreported income are common triggers. Real estate investors face extra scrutiny because rental returns involve multiple income streams, complex deductions, and partnership structures.

Missing income is one of the biggest triggers: when the IRS receives a Form 1099 or Schedule K-1 showing income you didn't report, your return must match what third parties report.
Unusually large deductions also attract attention. If expenses spike suddenly or your deduction percentage far exceeds industry norms, the IRS may investigate. Sloppy recordkeeping makes this worse, undocumented deductions are assumed inflated.
Information Services Unlimited provides specialized tax-saving and asset protection strategies designed to help investors legally minimize tax liabilities and prevent IRS audits.
Step 1: Reconcile All Income Sources and Information Returns
Your first step is matching every dollar the IRS knows about to your tax return, a reconciliation process critical for minimizing IRS audit risk.
Information returns tell the IRS what you earned: 1099-INT for interest, 1099-DIV for dividends, 1099-MISC for miscellaneous income, and Schedule K-1 for partnership or S-corp income.
Start by collecting all information returns you received:
- 1099-INT from banks and brokerage accounts
- 1099-DIV from dividend-paying stocks and mutual funds
- 1099-S from real estate sales
- Schedule K-1 from partnerships or S-corps you own
- 1099-NEC or 1099-MISC from business income
- 1099-B from brokerage account transactions
Next, reconcile line by line: interest on Schedule B, dividends on Schedules B and D, partnership income on Schedule E, and real estate sales on Schedule D.
Many investors forget a 1099 or put income in the wrong place. IRS systems automatically match 1099s to returns, and a mismatch triggers a notice or audit.
Create a reconciliation spreadsheet listing each information return, its amount, and where you reported it. This catches errors before you file.
Step 2: Document Rental Property Tax Deductions Thoroughly
Rental property deductions are where many audits start. The IRS knows some investors overstate or fabricate them. Your job is to prove every deduction is real and necessary.
Common rental property deductions include:
- Mortgage interest (not principal)
- Property taxes
- Insurance premiums
- Repairs and maintenance
- Property management fees
- Utilities you pay
- Advertising for tenants
- Depreciation
- Travel to manage properties
Keep detailed records for each deduction category, broken down by type and by property, tracking each rental separately.
Repairs versus improvements is critical: repairs are deductible, while improvements are capitalized and depreciated. Painting a room is a repair; replacing the roof is an improvement. Deducting something that should be capitalized means back taxes plus penalties.
Keep receipts for everything, repair invoices, property tax bills, supply receipts. These documents prove your deductions are real.
For large or unusual expenses, get written estimates or invoices from contractors. Don't claim $5,000 in repairs without documentation.
Step 3: Establish Real Estate Investor Tax Recordkeeping Systems
Your recordkeeping system is your defense in an audit. Without organized records, you cannot prove your deductions.
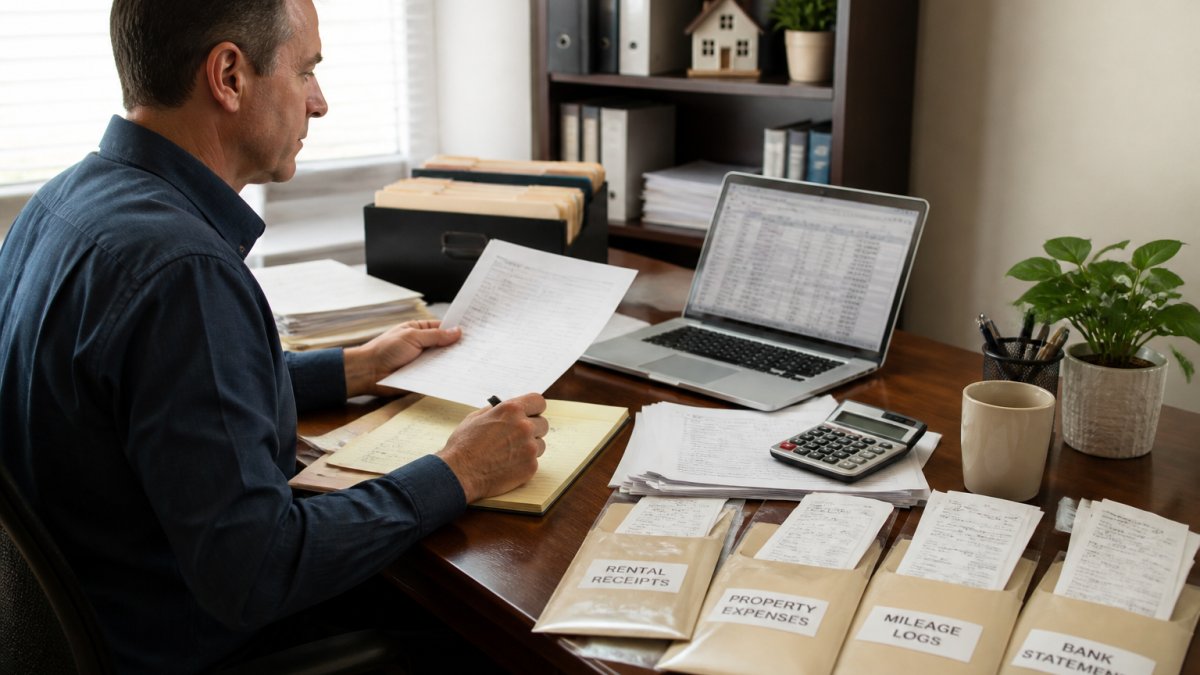
Set up a system before the year starts. Use digital or paper organization, many investors combine both, but be consistent.
Digital systems work well for most investors:
- Spreadsheet for monthly income and expenses by property
- Cloud storage folder for receipts and invoices
- Accounting software like QuickBooks or Wave
- Mobile app for photographing receipts on the go
- Bank and credit card statements downloaded monthly
Paper systems require more discipline but work if you're organized:
- Separate folder for each property
- Monthly envelope for receipts
- Ledger for tracking expenses
- Filing system organized by expense category
Whichever system you choose, enter data monthly, not annually. Monthly entry catches errors early; annual entry means forgotten details and lost receipts.
Categorize expenses properly, repairs, maintenance, insurance, property tax, mortgage interest, utilities, advertising, management fees, travel. This eases tax prep and shows the IRS you're organized.
Track rental income separately. Keep records of rent received, deposits, tenant information, and lease agreements to support income reporting and prove active management.
Step 4: Know How Long to Keep Rental Property Tax Records
The IRS can audit different time periods depending on the situation, so knowing how long to keep records keeps you prepared.
Generally, keep tax records for three years, the statute of limitations for auditing most returns (IRS audits). If the IRS doesn't contact you within three years, they generally cannot audit that year.
But three years isn't safe for real estate investors, keep records at least seven years.
For rental properties, keep these records:
- All tax returns filed (at least seven years)
- Receipts and invoices for all deductions
- Bank statements showing rental income and expenses
- Mortgage statements showing interest paid
- Property tax bills and insurance policies
- Lease agreements with tenants
- Records of repairs and improvements
- Depreciation schedules
- Basis calculations for each property
Keep depreciation records longer than seven years.
For sold properties, keep records indefinitely. The IRS can examine whether your depreciation deductions were correct, going back to when the property was placed in service.
More Insiders Secrets To Avoid IRS Audits →
Store records safely, cloud backup plus secure physical storage. If you can't produce records when the IRS asks, you lose the deduction even if you incurred the expense.
| Record Type | How Long to Keep |
|---|---|
| Tax returns and supporting documents | 7 years minimum |
| Receipts and invoices | 7 years minimum |
| Property records and basis information | Life of ownership + 3 years |
| Depreciation schedules | Life of ownership + 3 years |
| Mortgage and property tax records | 7 years minimum |
| Tenant lease agreements | 7 years after tenant moves out |
Step 5: Report Investment Losses Accurately and Support Them
Investment losses require careful reporting. The IRS scrutinizes loss claims because they reduce taxable income. Unsupported or inflated losses trigger audits.
Capital losses must be reported on Schedule D (Form 1040), whether from stocks, bonds, or rental property, and matched to the specific investment that generated them.
To report losses correctly, you need cost basis, what you paid plus improvements.
When you sell, calculate your loss:
- Sale price minus basis equals gain or loss
- If the sale price is less than basis, you have a loss
- Report the loss on Schedule D
Rental losses are more complex. When expenses exceed rental income, the loss can offset other income, but passive activity loss rules limit how much you can deduct each year.
Keep detailed records supporting your loss claims:
- Purchase documents showing what you paid
- Improvement receipts showing basis additions
- Sale documents showing the sale price
- Calculation showing the loss amount
- Documentation of expenses that created the loss
The IRS challenges loss claims when documentation is weak.
For real estate losses, document why the property lost money, a down market, vacancies, unexpectedly high repairs.
Step 6: Avoid Unusually Large or Inconsistent Deductions
The IRS uses statistical analysis to flag returns that deviate significantly from industry norms.
Large deductions relative to income are a red flag. If rental income is $40,000 but deductions are $35,000, the IRS notices, most rentals don't operate at near-breakeven.
Inconsistent deductions also trigger audits. Claim $8,000 in repairs one year and $25,000 the next with no explanation, and the IRS questions the spike.
Document any major changes:
- If repairs spiked, explain why. Was there storm damage? Did the roof fail?
- If you added a property, show when it was added and why expenses increased
- If you changed management companies, explain the timing
- If you made capital improvements, document them separately from repairs
Income consistency matters too. If rental income jumps 50% with no explanation, the IRS may investigate. Document the reason, raised rents, new properties, or reduced vacancies.
Compare deductions to industry benchmarks.
If deductions are unusually high, either reduce them to realistic levels or document why your property is different.
Step 7: Respond Promptly to Audit Notices
If you receive an audit notice, respond quickly, delays give the IRS reason to be suspicious.
The IRS sends audit notices by mail explaining which tax year is examined and what information they want.
Gather the requested documentation immediately. Missing IRS deadlines can result in the agency making assumptions against you.
Organize your response clearly.
Provide complete documentation:
- Original receipts and invoices
- Bank and credit card statements
- Property tax bills and insurance policies
- Contractor estimates and invoices
- Lease agreements with tenants
- Any written communications about the items being questioned
Provide exactly what's requested, no more, no less.
Consider professional help for complex issues like depreciation, partnership accounting, or loss limitations.
Respond in writing, not by phone. Keep copies of everything, use certified mail for proof of delivery, and document all communications with the IRS.
If the IRS proposes adjustments you disagree with, you have appeal rights explained in the notice. Many audits are resolved through discussion and clarification, so remain calm and professional.
Minimizing IRS audit risk for investors comes down to organization, documentation, and accuracy. Information Services Unlimited provides specialized resources like More Insider Secrets to Avoid IRS Audits, which walks you through proven methods for maintaining accurate records and structuring your investments for compliance. Our How to Audit-Proof Your Business From The IRS report covers additional strategies specifically designed for real estate professionals.


Frequently Asked Questions
What are the biggest IRS audit red flags for real estate investors?
The most common audit triggers include unreported rental income, missing or mismatched Forms 1099, unusually high deductions relative to income, inconsistent year-over-year reporting, and poor documentation of business expenses. Investors with multiple properties face higher audit risk if their records are disorganized or deductions appear aggressive. Maintaining accurate records and reconciling all income sources significantly reduces red flags.
How long should real estate investors keep tax records for rental properties?
The IRS generally allows a three-year statute of limitations for most tax returns, but you should keep records for at least seven years. For rental properties, maintain documentation for the entire holding period plus seven years after sale to support depreciation recapture and basis adjustments. This includes receipts, repair invoices, mortgage statements, and depreciation schedules. Longer retention protects you if the IRS questions your deductions or cost basis.
What documentation do I need to support rental property tax deductions?
Keep receipts, invoices, and statements for all rental expenses: repairs, maintenance, property management fees, insurance, utilities, and mortgage interest. For capital improvements, retain contracts and before-after photos. Maintain a property ledger showing date, amount, and description of each expense. For vehicle deductions, track mileage logs. For depreciation, keep the original purchase agreement and cost basis documentation. Organized, itemized records are your strongest defense against audit adjustments.
Should I use an LLC to reduce my audit risk?
An LLC does not directly reduce audit risk, the IRS audits the individual return and underlying business records, not the entity type. However, proper LLC structuring improves compliance by separating business and personal finances, which makes recordkeeping cleaner and deductions easier to defend. The real audit protection comes from accurate reporting, complete documentation, and consistent business practices, regardless of whether you operate as a sole proprietor, LLC, or partnership.