

Table of Contents
- What a Holding Company Does for a Rental Property Portfolio
- Series LLC for Real Estate: One Parent, Many Protected Cells
- Tax Implications of Real Estate Holding Companies
- Cost of Forming an LLC for Rental Property
- Financing and Mortgage Implications of a Holding Company Structure
- Operational Workflow: Managing Multiple LLCs With One Tax Return
- Exit Strategy and State-Specific Considerations
- Conclusion
- Frequently Asked Questions
Last Updated: September 20, 2026
What a Holding Company Does for a Rental Property Portfolio
Setting up a rental property holding company separates ownership from operations, creating a legal buffer between your personal wealth and each property's risks. A holding company is a parent entity that owns the membership interests of subsidiary LLCs, each holding one or more rentals. This guide from Information Services Unlimited explains the structure, tax mechanics, and operational details most investors miss.
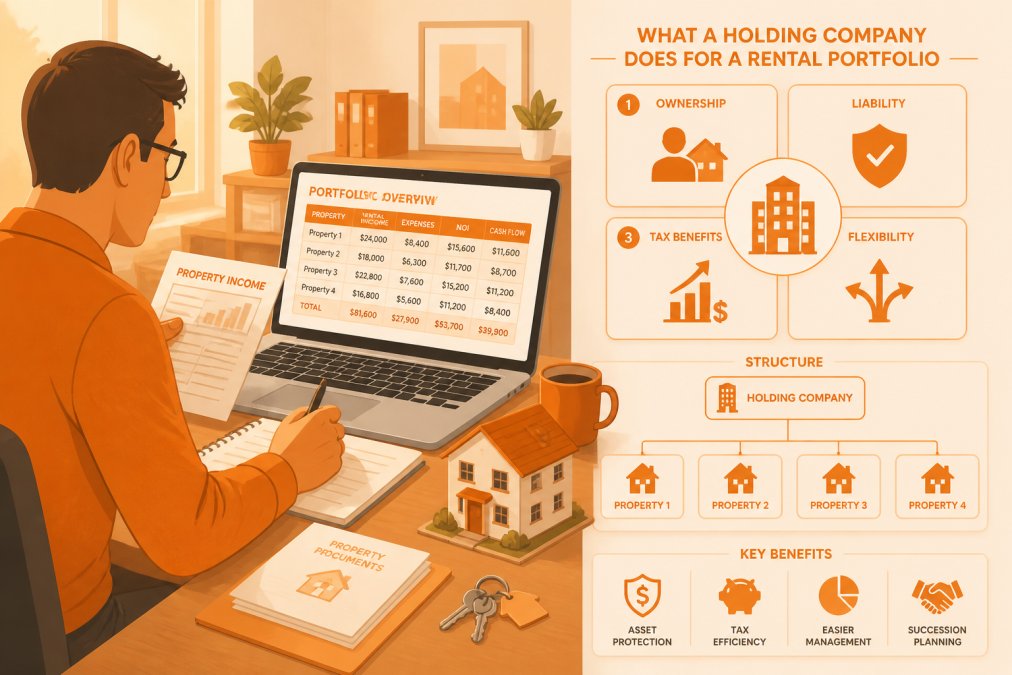
How the Parent-Subsidiary Structure Works
The holding company sits at the top as the parent company, and each rental property sits inside its own subsidiary LLC. The parent holds each subsidiary's membership interests; each subsidiary holds title to its property.
Series LLC for Real Estate: One Parent, Many Protected Cells
A series LLC is a single legal entity divided into separate cells, each protecting a distinct property or group of properties. It delivers the same asset segregation as multiple LLCs with only one articles of organization filing and one set of annual fees in states that recognize it.
Tax Implications of Real Estate Holding Companies
A properly structured holding company does not create a second layer of tax. By default, a multi-member parent is a pass-through entity: profits flow to your personal return and are taxed once. The holding company is a legal container, not a tax event.
IRS instructions for Form 1065 partnership returns
Pass-Through Treatment and the 1065 Filing
When the parent is taxed as a partnership, the IRS treats it as a conduit. Income, deductions, and credits pass through to the owners' personal returns, and the entity pays no federal income tax. The parent's Form 1065 reports aggregate activity, and each owner receives a K-1 reflecting their share.
Cost of Forming an LLC for Rental Property
The cost of forming an LLC for rental property varies by state, but recurring expenses matter more than the initial filing fee. Budget for the entity formation fee, a registered agent, annual report fees, and accounting work to keep each entity's books separate.
| Cost Category | Typical Frequency | What Drives the Amount |
|---|---|---|
| State formation filing | One-time per entity | State fee schedule |
| Registered agent | Annual per entity | Commercial vs. self-agent |
| Annual report / franchise fee | Annual per entity | State formula |
| Separate bookkeeping | Monthly | Number of bank accounts |
| Tax return preparation | Annual per entity | 1065 plus K-1s |
Financing and Mortgage Implications of a Holding Company Structure
Financing is the single biggest constraint on how you build the structure: the entity that holds title is the entity the lender underwrites, and most lenders are not set up to underwrite a subsidiary owned by a parent.
Why Conventional Loans Resist the Structure
A conventional residential mortgage, backed by Fannie Mae and Freddie Mac guidelines, is written for a natural person or, in limited cases, a single-purpose LLC taking title directly. A subsidiary LLC owned by a separate parent does not fit that box. When a lender sees a two-tier chain of ownership, the loan typically gets pushed into commercial underwriting: shorter amortization, higher rates, and a balloon feature.
The Due-on-Sale Clause in Plain Terms
A standard mortgage contains a due-on-sale clause, also called a due-on-transfer or acceleration clause, letting the lender demand full repayment if title transfers without consent. Moving a mortgaged property into a subsidiary is a transfer, even though you still own it through a different entity.
What Lenders Actually Ask For
When you approach a lender about a holding structure, for consent, a refinance, or a new purchase loan, expect to produce a document package. Underwriters typically want:
- The parent entity's operating agreement and formation documents
- The subsidiary's articles of organization and operating agreement
- A clear chain-of-ownership diagram showing who owns what
- Personal financial statements and guarantees from the principals
- Rent rolls and leases for the properties being financed
- Evidence that the entities are in good standing in their states of formation
Personal Guarantees and Recourse
Even when a lender finances a property held in a subsidiary, it will almost always require a personal guarantee from the principals. The liability shield you built for tenant lawsuits does not extend to the mortgage, if the loan defaults, the lender can pursue you personally. The holding structure protects against operating liabilities, not the debt on the property.
Refinancing and the Seasoning Question
Refinancing a property held in a subsidiary adds another layer. Some lenders impose a seasoning period, commonly six to twelve months, and many will not refinance a property transferred into an entity they did not originally underwrite. If you plan to buy, stabilize, and refinance, map out the entity question before you close.
The LLC Master Machine Asset Protection →
A Practical Sequencing Rule
Most practitioners find the cleanest path is: acquire and finance in the name the lender will accept, then evaluate a transfer into the holding structure once the loan is seasoned and you have the lender's position in writing. Build the liability shield, but do not let it cost you the loan.
Operational Workflow: Managing Multiple LLCs With One Tax Return
Running several entities does not require several tax returns or checking accounts if the structure is built correctly. A coordinated multiple LLC tax strategy maintains liability protection for individual properties while consolidating financial management and reporting. The hard part is the daily bookkeeping discipline that keeps entities legally separate while the tax filing stays consolidated.

The Account Structure That Actually Works
Open one operating account for the parent and a dedicated account for each subsidiary. Do not commingle funds and track splits in a spreadsheet, that is the fastest way to lose the corporate veil. Each subsidiary's rent deposits go into its own account, and its property expenses come out of the same account.
- Capital contribution, the parent contributes cash to the subsidiary. No tax event, but it increases the parent's basis in the subsidiary and should be recorded on the books of both entities.
- Inter-company loan, the parent lends to the subsidiary. Requires written terms, a stated interest rate at or above the applicable federal rate, and a repayment schedule. Without those, the IRS can recharacterize the loan as a distribution.
- Management fee, the parent charges the subsidiary for services actually rendered (bookkeeping, oversight, leasing). The fee is deductible by the subsidiary and taxable income to the parent, so it nets out at the consolidated level but must be supported by a written agreement and evidence the services were performed.
The Monthly Close
A workflow that holds up under scrutiny:
- Route every rent payment into the subsidiary that owns the property.
- Pay property expenses from that same subsidiary account.
- Record any inter-entity transfer with a memo describing its purpose, contribution, loan, or fee.
- Reconcile each account monthly and store the records by entity.
- Review the parent's consolidated position to confirm the entities still balance.
- At year end, prepare the parent's Form 1065 and the required schedules for each subsidiary.
The fiduciary duty you owe as manager of each entity means the accounts are not interchangeable. Taking a distribution from one subsidiary to cover another's shortfall without documentation creates a fact pattern a plaintiff's attorney or auditor can use to argue the entities are not separate.
How the 1065 Ties to the Subsidiaries
When the parent is taxed as a partnership, it files Form 1065 and issues Schedule K-1s to its owners. Each subsidiary may be a disregarded entity, a partnership, or a corporation depending on formation elections. The parent's return reports aggregate activity, but subsidiary records support the numbers.
One Checking Account, Multiple Entities
Some practitioners advocate a single checking account with sub-ledgers per entity. This can work, but it requires strict internal controls: every transaction coded to the correct entity when recorded, and bank statements reconcilable to each entity's books. Without that discipline, separate accounts are safer, a few extra accounts cost far less than losing the liability shield.
Exit Strategy and State-Specific Considerations
Selling a property held inside a subsidiary requires planning before listing. The buyer may want the property, the LLC, or the membership interests, and each path carries different tax liability and capital gains consequences. Selling membership interests can transfer built-in liabilities to the buyer, which many purchasers refuse without a price adjustment.
IRS publication on selling business assets and capital gains
Conclusion
Building a rental property holding company is not complicated, but it is unforgiving of shortcuts. Investors get burned when they form entities and treat them as paperwork rather than separate legal persons with their own accounts, agreements, and records.
Frequently Asked Questions
Should I put my rental property in a holding company?
A holding company makes sense when you own multiple rentals and want to separate liability from control. The parent company owns the subsidiary LLCs that hold each property, so a lawsuit against one rental stays contained. You also gain centralized management and cleaner books. If you own one or two properties with low equity, the cost and paperwork may outweigh the benefit. Investors with growing portfolios typically see the strongest case for a rental property holding company.
Do I need a separate LLC for every rental property I own?
Separate subsidiary LLCs are the standard way to isolate liability per property. If one tenant sues over a fall at Property A, only that LLC's assets are exposed. Some states allow a series LLC for real estate, where each series holds one property under a single parent filing. The trade-off is higher formation and maintenance costs versus stronger asset segregation. Many investors start with one LLC per property and consolidate administration through a parent holding company.
What is the cost of forming an LLC for rental property?
State filing fees for a single LLC generally run from about $50 to $500, with annual report fees on top. Multiply that by each property if you form separate subsidiaries. You will also pay a registered agent and possibly a franchise tax. A structured program like the LLC Master Machine Asset Protection Program, available for $995, includes a comprehensive operating agreement with 240+ legal provisions, tax elections, and audio training explaining the setup from beginning to end for new and existing LLCs.
What are the disadvantages of a holding company for rental portfolios?
The main drawbacks are cost and complexity. Each subsidiary LLC needs its own formation documents, registered agent, and annual filings, which adds up across a portfolio. Lenders may also resist financing a property owned by a subsidiary, and some due-on-sale clauses can be triggered by transferring title. You must keep separate bank accounts and records for each entity to preserve the corporate veil. Skipping those formalities can void the liability shield you paid to create.