

Last Updated: November 14, 2026
Quick Summary
To learn how to vet a real estate tax professional, verify their credential is active, confirm they have real rental property experience, and compare written fee terms. Check licenses through state boards, the IRS directory, or state bars, then ask specific questions about real estate professional status and audit support before hiring.
- Verify CPA licenses through the state board of accountancy's online lookup.
- Confirm enrolled agent status using the IRS directory of federally authorized practitioners.
- Ask how many rental property clients the advisor serves and what share of practice is real estate.
- Ask how they document hours for real estate professional status using a contemporaneous log.
- Get a written fee quote and confirm whether audit representation is included or billed separately.
Table of Contents
- Step 1: Verify Real Estate Tax Professional Credentials
- Step 2: Confirm Experience With Rental Properties and Real Estate Status
- Step 3: Prepare Your Records and Questions Before the Meeting
- Step 4: Compare Fees, Engagement Terms and Service Boundaries
- Red Flags of a Bad Tax Preparer to Walk Away From
- Booking Your Real Estate Tax Consultation With Confidence
- Frequently Asked Questions
Learning how to vet a real estate tax professional is one of the most consequential financial decisions a rental property investor makes. The wrong advisor can miss deductions, mishandle depreciation, or leave you exposed in an IRS audit.
A real estate tax professional is a CPA, enrolled agent, or tax attorney who prepares returns and advises on rental income, depreciation, passive losses, and entity structure. Many investors assume any tax preparer can handle their portfolio. That assumption is often where costly mistakes start.
Many investors rely on advisors who lack specialized real estate experience. The concept behind the 80-15-5 idea is that a large share of general tax advisors may not fully understand real estate tax planning.
Here is what poor advice commonly costs investors:
- Missed legitimate rental deductions
- Inefficient property or entity structuring
- Misunderstood depreciation rules
- Overlooked long-term tax planning opportunities
Careful vetting protects your profits and your position if the IRS ever asks questions. The steps below show how to do it.
Step 1: Verify Real Estate Tax Professional Credentials
Start by confirming that your candidate holds a valid credential and that the credential actually authorizes the work you need done. A CPA license is issued by a state board of accountancy, an enrolled agent is authorized to practice before the IRS, and a tax attorney is licensed by a state bar (Understanding tax return preparer credentials and qualifications). Each one can prepare a return, but they are not interchangeable when a rental portfolio gets complicated. Compare how each credentialed provider's service scope differs before deciding who to trust.
Verification is a five-minute exercise if you know where to look:
- CPA: Search the state board of accountancy's online license lookup for the state where the preparer practices. Confirm the license status is active and check the expiration date. Most boards also publish disciplinary actions and public reprimands.
- Enrolled agent: Use the IRS directory of federally authorized tax practitioners (FAQs Directory of Federal Tax Return Preparers with Credentials and Select Qualifications). Confirm the EA number is current and that the preparer holds active status.
- Tax attorney: Check the state bar's member directory for active status and any public discipline. A tax attorney who is also a CPA will appear in both lookups, verify both.
- Preparer Tax Identification Number (PTIN): Every paid preparer must have a current PTIN (PTIN requirements for tax return preparers). Ask for it and confirm it is active through the IRS preparer directory.
Credential differences and scope of practice
Not every credential covers the same work, and the scope matters more than the letters after the name.
- CPA: Broad accounting and attest experience; strongest for entity structuring, multi-state apportionment, and financial statement work. A CPA can represent you before the IRS only if the CPA also holds a valid power of attorney and is authorized to practice, most are, but confirm.
- Enrolled agent: Focused on federal tax and authorized to represent taxpayers before the IRS in audits, collections, and appeals. Strong choice when your biggest exposure is an IRS notice or a rental-loss examination.
- Tax attorney: Handles legal questions, entity formation, partnership agreements, like-kind exchanges, and Tax Court litigation. A tax attorney is the right call when the issue is legal rather than computational.
Match the credential to your biggest need. A portfolio with multiple LLCs and multi-state rentals may call for a CPA with real estate experience. An audit notice on a return claiming real estate professional status may call for an enrolled agent or a tax attorney who litigates. A single-property investor with a clean return may be well served by an experienced EA.
Watch out: a preparer who lists a credential but cannot produce an active license number, or whose license shows a suspended status, is a hard stop regardless of how impressive the pitch sounds. Verify before you share a single document.
The credentials below differ in what they authorize, so match the credential to your biggest need.
| Credential | Best for | Key difference |
|---|---|---|
| CPA | Entity structuring and multi-state rentals | Broad accounting and attest experience |
| Enrolled agent | IRS notices and rental-loss examinations | Focused on federal tax and IRS representation |
| Tax attorney | Legal questions and Tax Court litigation | Handles entity formation and like-kind exchanges |
Step 2: Confirm Experience With Rental Properties and Real Estate Status
Credentials alone do not prove real estate expertise. Ask how many rental property clients the professional serves and how much of their practice focuses on real estate. A practitioner who handles mostly small business returns may not know the rules that matter most to you.
Ask specifically whether they understand real estate professional status. This designation can change how rental losses are treated, and it depends on strict participation rules. A good advisor can explain the basics and tell you what records you would need to support it.
Watch for this common mistake: some clients assume they qualify for real estate professional status without tracking their hours. An experienced advisor will raise this before you file, not after an audit letter arrives.
Step 3: Prepare Your Records and Questions Before the Meeting
Gather your records before the first call. Strong preparation shows the advisor you are serious, lets them give specific answers instead of generalities, and gives you a fair basis for comparing candidates.
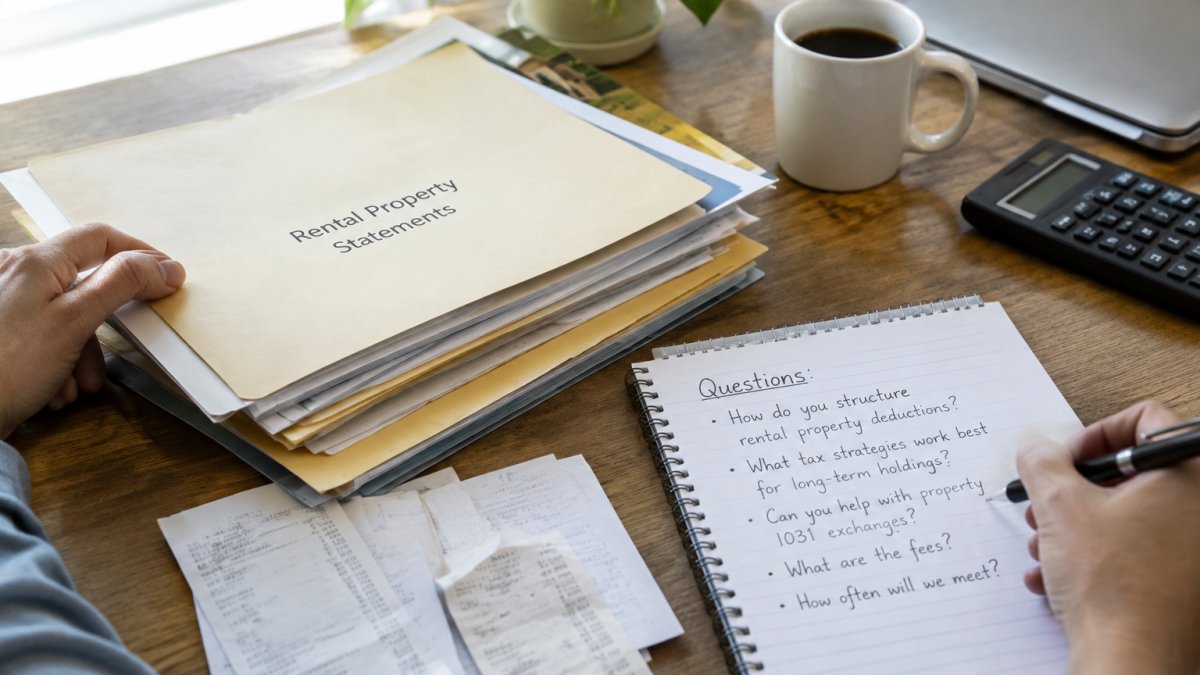
Bring these items to every consultation:
- Property purchase closing statements and settlement statements
- Prior three years of federal and state tax returns, including all schedules and K-1s
- Rental income and expense ledgers, ideally by property
- Depreciation schedules and any prior cost-segregation studies
- Entity documents for any LLCs, partnerships, or S corporations
- Time logs and calendars if you believe you qualify for real estate professional status
- Any IRS notices, state notices, or audit correspondence
Questions to ask a real estate tax professional
Use the same questions for every candidate and write down the answers. A reusable scorecard turns a vague impression into a comparison you can defend.
- How many rental property clients do you currently serve, and what share of your practice is real estate?
- Which credentials do you hold, and can you provide the license or EA number so I can verify it?
- How do you evaluate and document real estate professional status, including the 750-hour test and the more-than-half test?
- How do you handle material participation for short-term rentals and cost segregation?
- What is your experience with IRS audits of rental returns, and who represents me if one occurs?
- How do you handle depreciation recapture when a property is sold?
- Will I work directly with you or with a staff member, and who signs the return?
- What records do you need from me, in what format, and on what schedule?
- How do you handle amended returns, and is that included or billed separately?
- What is your process for year-end planning versus filing-only work?
Score each answer on a simple 1-3 scale: 1 for vague or evasive, 2 for adequate, 3 for specific and documented. A candidate who scores 3s across the board is worth a second meeting; a candidate who cannot answer questions 3 through 5 specifically is not.
A client-ready evidence workflow
The strongest vetting signal is whether the advisor has a repeatable process for the records that drive real estate tax positions. Ask them to describe it, and expect something like this:
- Calendar and time logs: A contemporaneous log of hours by property and activity, reviewed quarterly rather than reconstructed in April.
- Property records: Closing statements, improvement receipts, and a depreciation schedule updated each year.
- Entity records: Operating agreements, capital accounts, and K-1 tie-outs.
- Communication trail: Written advice on material positions, especially real estate professional status and grouping elections.
If the advisor cannot describe a workflow for organizing these records before the engagement begins, you will likely be the one building it under deadline pressure.
Watch out: an advisor who asks for your records but never asks how you track hours is signaling that real estate professional status will be handled casually, which is exactly the position most likely to fail on audit.
Step 4: Compare Fees, Engagement Terms and Service Boundaries
Fees vary widely, so ask for a written quote before you commit. Common fee structures include hourly billing, flat fees per return, and monthly retainers. Each suits a different portfolio size.
Read the engagement letter carefully. See a clear breakdown of CPA firm fee models to compare against the quotes you receive. It should state what work is included, what is excluded, and whether audit representation costs extra. Unclear service boundaries are a frequent source of surprise bills.
- Confirm whether the fee covers year-end planning, not just filing
- Ask whether audit support is included or billed separately
- Check how the advisor handles mid-year questions
Red Flags of a Bad Tax Preparer to Walk Away From
Some warning signs should end the search immediately:
- Promises of guaranteed tax savings or large refunds
- Pressure to sign before you review the paperwork
- Refusal to explain how a strategy works
- Suggestions to hide income or inflate deductions
- No valid credential or a license that cannot be verified
- Fees charged as a percentage of your refund
Unrealistic tax-savings promises are a clear danger sign. Legitimate advisors explain the rules and the risks, and they do not guarantee outcomes the IRS controls.
Booking Your Real Estate Tax Consultation With Confidence
You now have a practical checklist: verify credentials, confirm real estate experience, prepare records and questions, and compare fees and terms in writing. Use the same criteria for every candidate so the comparison stays fair. Follow a step-by-step guide to switching real estate accountants if you decide your current accountant isn't working.
If you want a deeper framework, the Information Services Unlimited guide 80-15-5" Stop The Epidemic Of Bad Tax Advisors ($25.00) walks through how to spot poor advice before it costs you.
Before your first meeting, write down your portfolio size, your entity structure, and your biggest tax question. That short summary will make every consultation more productive and help you choose a professional who can protect your returns for years to come.
Frequently Asked Questions
What are the red flags of a bad tax preparer?
Watch for preparers who promise guaranteed refunds or unusually large tax savings, charge fees based on a percentage of your refund, refuse to sign the return they prepare, or ask you to leave the refund line blank. Also be wary of anyone who does not hold a valid PTIN, cannot explain how real estate losses are treated, or pushes aggressive strategies without documentation. A reputable professional will discuss your situation, explain the rules that apply, and welcome your questions.
What credentials should a real estate tax professional have?
Look for a CPA, an Enrolled Agent, or a tax attorney, since each is authorized to represent clients before the IRS. Confirm the license is active through the relevant state board or the IRS directory of federally authorized tax practitioners. Ask whether the professional has specific experience with rental real estate, real estate professional status, and passive activity rules, because general tax training does not always cover these areas in depth.
How do you vet a tax professional for real estate investing?
Start by verifying credentials, then ask how many real estate investors they serve and what share of their work involves rental properties. Request a clear explanation of their approach to the 750-hour test and the more-than-half test, and ask how they document participation hours. Compare fee structures in writing, and check whether they offer representation if you are audited.
What questions should I ask a real estate tax professional before hiring them?
Ask how they track time for real estate professional status, what records they require, and how they handle material participation for rental activities. Find out whether they have represented clients in IRS audits, what their fees cover, and who will work on your return. Ask how they stay current with tax law changes and whether they will explain their recommendations in writing.
