

Quick Summary
Capital gains tax applies to the profit from selling investment property above its adjusted basis, and the rate depends on how long you held it and your income bracket. Because depreciation recapture and long-term gains are taxed differently, a rate change affects each property in a portfolio by a different amount.
- Property held one year or less is taxed as short-term gain at ordinary income rates.
- Adjusted basis rises with capital improvements and falls with depreciation claimed or allowable.
- Depreciation recapture is taxed separately from the long-term capital gain portion.
- Rank properties by after-tax rate sensitivity, not raw gain, to decide sale order.
- Treat portfolio results as planning estimates and rerun them when a bill advances.
Table of Contents
- How Capital Gains Tax Works on Investment Real Estate
- Capital Gains Tax on Investment Property: Where Changes Hit Hardest
- Modeling Portfolio-Level Impact of a Rate Change
- How the 1031 Exchange Changes the Math on Reinvestment
- Deductions When Selling a House and the Home Sale Exclusion
- How Investors Can Plan for Proposed Tax Changes
- Choosing Your Next Step in Portfolio Tax Planning
- Frequently Asked Questions
How Capital Gains Tax Works on Investment Real Estate
Capital gains tax is the federal levy on the profit realized when an investment property is sold for more than its adjusted basis (Topic no. 409, Capital gains and losses). For a real estate portfolio, the rate you pay depends on how long you held the asset and what income bracket you fall into, which means a single rule change can move your after-tax return on every property you own. Understanding these mechanics is the first step toward modeling how proposed changes would affect your holdings.
Short-term versus long-term capital gains
The holding period decides everything. Property held one year or less produces short-term gains, which are taxed as ordinary income at your marginal federal rate (Topic no. 409, Capital gains and losses). Property held longer than one year qualifies for long-term rates, which are lower for most brackets. For an investor who flips or rapidly rotates rentals, the gap between these two treatments can be the difference between a modest and a severe tax bill.
Many investors assume the one-year mark is a formality. It is not.
Cost basis, adjusted basis and depreciation recapture
Your taxable gain equals the sale price minus your adjusted basis, not your original purchase price. Adjusted basis starts with what you paid, including certain closing costs, then rises with capital improvements and falls with depreciation you claimed or were entitled to claim over the years you owned the property.
That last point matters more than most investors expect. Depreciation recapture taxes the portion of your gain attributable to depreciation deductions you took, generally at a maximum federal rate that can exceed the standard long-term capital gains rate.
Capital Gains Tax on Investment Property: Where Changes Hit Hardest
Investment property is where changes to capital gains rules hit hardest, because investors can rarely avoid realizing gains on purpose and often hold appreciated assets for years. Primary residences enjoy a separate exclusion that shields a large share of gain from tax, while rental and commercial holdings do not. Any rate increase therefore lands squarely on the gains that accumulate inside a portfolio.
Modeling Portfolio-Level Impact of a Rate Change
Most guides discuss capital gains one property at a time. A portfolio view is more useful because a single rate change hits every holding at once, and the properties with the largest embedded gain are rarely the ones an investor expects. The goal of a portfolio model is to rank holdings by after-tax sensitivity, then use that ranking to decide what to sell, hold, exchange, or restructure if a bill advances.
Build the property-level inputs first
Create one row per property with these columns: purchase price, adjusted basis, current market value, accumulated depreciation, years held, expected selling costs, and current mortgage balance if you need net proceeds. Adjusted basis is the number most investors get wrong. It starts with the purchase price plus certain closing costs, rises with capital improvements, and falls by depreciation you claimed or were entitled to claim. If your basis is overstated, every downstream tax estimate is wrong.
Run the gain split, not just the headline gain
For each property, calculate three numbers before you apply any rate:
- Total gain = expected sale price minus adjusted basis
- Recapture portion = accumulated depreciation, taxed at the recapture rate for real property
- Long-term capital gain portion = total gain minus recapture, taxed at the applicable long-term rate
Then compute net after-tax proceeds as sale price minus selling costs minus total federal tax. Run the same row under current law and under your proposed-rate assumption, holding every other input constant. The difference between the two columns is the property's rate sensitivity.
A transparent example
Consider a rental purchased for $400,000 with $80,000 of capital improvements and $120,000 of accumulated depreciation. Adjusted basis is $400,000 + $80,000 − $120,000 = $360,000. If it sells for $650,000 with $40,000 in selling costs, the amount realized is $610,000 and total gain is $250,000. Recapture is $120,000; the remaining long-term gain is $130,000.
Now compare a second property held 15 years with a $600,000 long-term gain and only $30,000 of recapture. The same rate change moves far more dollars on the second property. That ranking, not the raw gain, should drive sale order.
Add sale timing to the model
A rate change rarely takes effect immediately. Model three timing cases: sell before the effective date, sell in the first year after, and hold five more years.
Watch out: a model built on stale basis figures or missed improvements will overstate tax and push you into a sale you did not need to make.
Treat the result as a planning estimate, not a filed return, and rerun it whenever a bill advances or your bracket changes.
The article walks through a three-column gain split for each property, using the same example figures.
| Gain component | How it is calculated | Tax treatment |
|---|---|---|
| Total gain | Sale price minus adjusted basis | Split into recapture and long-term portions |
| Recapture portion | Accumulated depreciation | Taxed at the recapture rate for real property |
| Long-term capital gain portion | Total gain minus recapture | Taxed at the applicable long-term rate |
| Net after-tax proceeds | Sale price minus selling costs minus federal tax | Compared under current law and proposed rate |
How the 1031 Exchange Changes the Math on Reinvestment
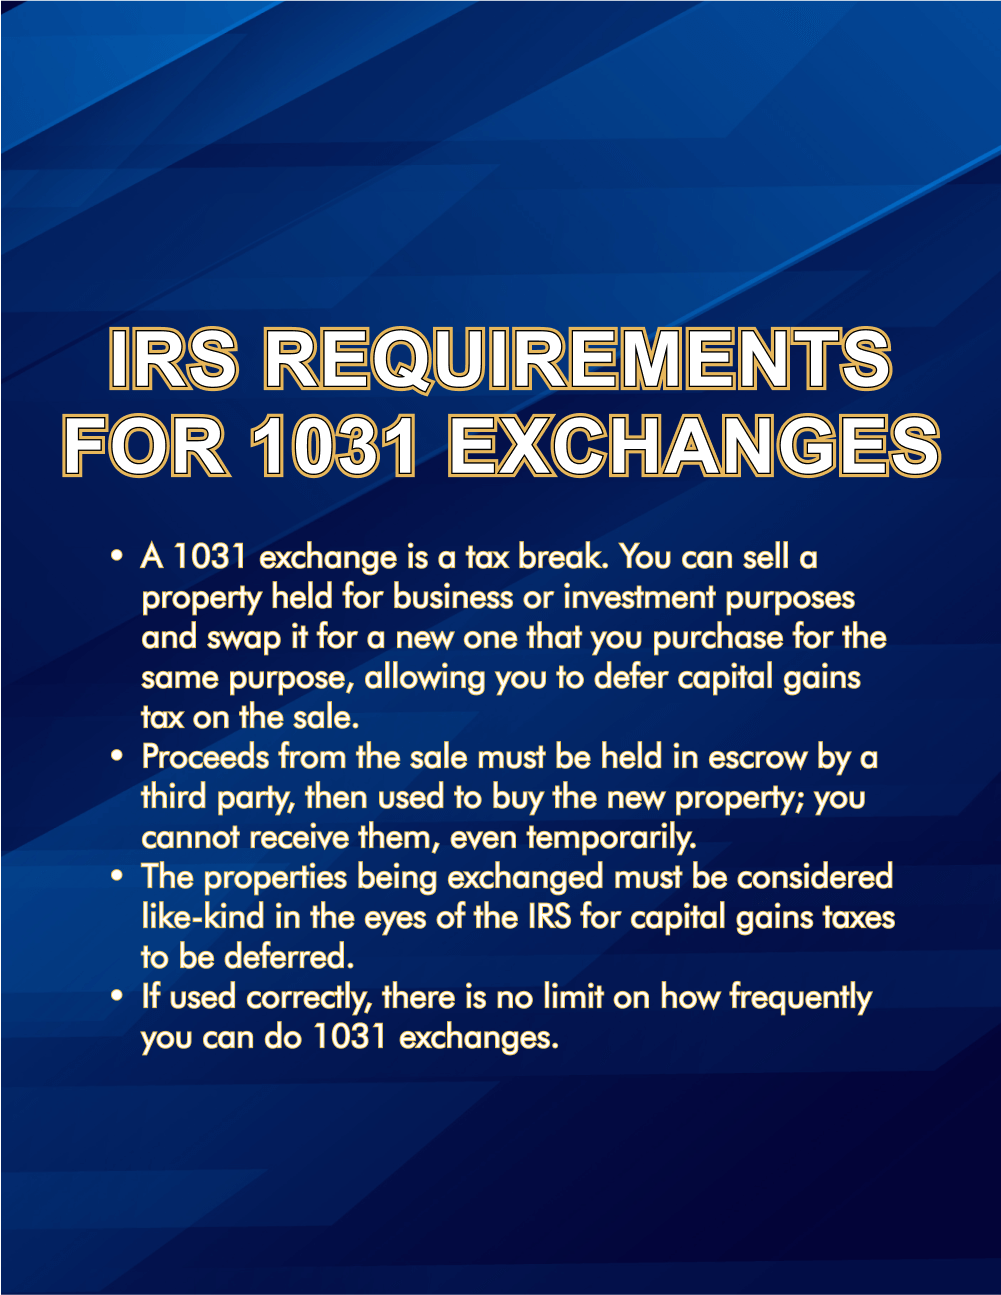
A 1031 exchange lets you defer recognition of gain when you sell an investment property and reinvest the proceeds in a like-kind replacement property (Like-kind exchanges - Real estate tax tips).
The rules are strict, and the IRS requirements for 1031 exchanges should be reviewed before relying on this strategy at irs.gov. See our resource on IRS requirements for 1031 exchanges for a step-by-step breakdown of the timelines.
For investors modeling a rate change, the 1031 exchange changes the calculation because it shifts when tax is paid rather than whether it is paid.
Investors comparing the strategy's mechanics can also review The 1031 Exchange to zero out taxes on the sale of your property, which walks through how deferral works in practice.
Deductions When Selling a House and the Home Sale Exclusion
Homeowners selling a principal residence may be able to exclude part of the gain from federal income tax, subject to ownership and use requirements; confirm current limits with the IRS at irs.gov (Topic no. 701, Sale of your home).
Selling costs such as commissions, title fees, and certain repair expenses reduce the amount realized, which lowers your gain. Keep receipts for every improvement, since capital improvements increase adjusted basis and reduce the taxable gain on sale.
How Investors Can Plan for Proposed Tax Changes
Planning for proposed changes means acting on what is law today while preparing for what might become law. The useful output is not a prediction. It is a written decision framework that tells you, in advance, which properties you would sell, hold, exchange, or restructure under each plausible outcome, so you are not making a rushed choice after a bill passes.
Step 1: Separate enacted law from proposals
Only enacted legislation changes your current-year tax, while proposals are scenarios rather than rules. Label each item in your file as enacted, proposed with a sponsor, or speculative. This keeps you from selling an asset to beat a rate change that never happens. Review IRS guidance and the actual bill text at irs.gov and congress.gov before you act on any headline.
Step 2: Rank holdings by embedded gain and recapture
Use the portfolio model to list each property by long-term gain, recapture exposure, and years held. The top two or three holdings usually account for most of the rate sensitivity. Those are the only properties that need a decision framework. The rest can stay on a hold-and-review schedule.
Step 3: Assign a default action to each scenario
For each high-exposure property, write four rows:
- If rates stay the same: hold, sell on your original schedule, or exchange.
- If long-term rates rise: consider accelerating the sale before the effective date, or exchanging to defer into the new regime.
- If rates fall: hold and harvest gains later at the lower rate.
- If rules change on exchanges or recapture: re-run the model, because a change to either rule can flip the answer.
A 1031 exchange is the main lever for deferral, but it shifts when tax is paid, not whether. The IRS requires identification of replacement properties within 45 days and completion within 180 days, and a qualified intermediary must hold the proceeds. If a rate increase is expected, deferral may be worth more, but the replacement property still has to meet the investment-use test and the deadlines. See our resource on IRS requirements for 1031 exchanges for the timeline detail.
Step 4: Sequence sales across tax years
Managing the timing of sales across tax years can keep gains in a lower bracket and avoid pushing you into a higher one in a single year. The Year-End Tax Planning Strategies for Real Estate Investors report covers related year-end planning topics. Pair that with a staggered sale schedule so no single year carries all the realized gain.
Step 5: Review ownership structure and estate exposure
Entity choice and inheritance rules can change the after-tax result as much as a rate change. Entity choice and inheritance rules can change the after-tax result as much as a rate change, so confirm the current rules with a tax professional. If a rate increase is likely, compare selling now, exchanging, and holding for a step-up. Confirm the current rules with a tax professional before relying on any of these outcomes.
Step 6: Document assumptions and set a review trigger
Record every rate assumption, effective date, and bracket in the file. Set a review trigger, such as a committee vote, a floor vote, or the release of new IRS guidance, so you revisit the model at the right moment rather than reacting to every news cycle.
Watch out: selling a property solely to beat a proposed rate that later fails can cost more in transaction costs and lost appreciation than the tax you avoided. Keep at least one scenario in which you do nothing.
Choosing Your Next Step in Portfolio Tax Planning
The right next step depends on how concentrated your gains are and how soon you expect to sell. Investors with a few high-gain properties should start with depreciation recapture and basis calculations, since those numbers drive every other decision.
If you want a structured path, How to Use Cost Segregation for Tax Savings 2026 and How to Vet a Real Estate Tax Professional? are related resources for further reading. Information Services Unlimited offers educational resources on real estate tax strategies for investors. Start with one property, build the model, and expand from there.
Last Updated: November 18, 2026
Frequently Asked Questions
Can a 1031 exchange defer capital gains tax on investment property?
A 1031 exchange, named after Section 1031 of the Internal Revenue Code, lets investors defer capital gains tax by reinvesting sale proceeds into a like-kind investment property. Review current IRS requirements for identifying and completing replacement property before relying on this deferral at irs.gov. The deferral is not elimination, so the deferred gain carries forward into the replacement property's basis.
How does the home sale exclusion work for real estate owners?
A primary-residence exclusion may apply to part of the gain from selling a home, subject to ownership and use requirements, and it does not apply to investment properties. Confirm current limits with the IRS at irs.gov.
What expenses can be deducted from capital gains when selling a property?
Selling costs and capital improvements can affect the taxable gain, so keep records of both.
How can investors reduce capital gains tax when selling investment real estate?
Common approaches include holding the property longer than one year to qualify for long-term rates, using a 1031 exchange to defer tax, documenting capital improvements to raise adjusted basis, and timing sales across tax years when income is lower. Investors should also estimate depreciation recapture before choosing a sale date.
